

Cashew—Expense Budget Tracker

- 672.00 Reviews
- 4.7
- Downloads
- 500,000+
Our take on Cashew—Expense Budget Tracker from Appgk
Managing money is rarely difficult because people cannot add numbers. The harder part is noticing spending at the right moment, understanding what a category means, and keeping the routine manageable when life is busy. Cashew—Expense Budget Tracker approaches that problem as a focused finance app rather than a full banking replacement. I found its appeal in the simple idea of recording expenses and checking budgets without turning everyday money management into a large administrative project.
It is developed by Dapper App Developer and is free to download, with optional in-app purchases ranging from $1.49 to $19.99 per item. The app is rated for Everyone, runs on Android 7.0 or later, and its current version is 6.6.11. Those details make it approachable for people using older Android devices as well as newer phones, although the experience still depends on how comfortable each person is with entering and reviewing financial information manually.
My overall impression is that Cashew works best for someone who wants a personal spending log and a clearer view of budgets, not someone looking for an all-in-one financial command center. It can support a calm, repeatable habit, but it rewards users who are willing to keep that habit going. The most important question is not whether it can display expense information; it is whether its workflow fits the way you actually live.
How clearly the app presents everyday money information
Readability and navigation
The strongest part of this kind of expense tracker is the separation between recording a purchase and reviewing the bigger picture. When I use a budgeting app, I want to answer three questions quickly: what did I spend, where did it go, and how much room is left? Cashew is built around that practical rhythm, which feels less intimidating than opening a general-purpose banking app filled with account balances, transfers, offers, and unrelated notifications.
Best Parts of Cashew—Expense Budget Tracker
Things to Keep in Mind About Cashew—Expense Budget Tracker
For a new user, the best approach is to begin with only the categories that match real spending. Adding every imaginable category at the start can make the budget feel like a form to complete instead of a tool to use. I would begin with essentials such as groceries, transport, housing, and personal spending, then add a category only when a recurring purchase genuinely needs separate attention. This creates a cleaner overview and reduces the amount of visual scanning required later.
That matters for readability. A budget screen becomes harder to understand when it contains too many small distinctions. A person who has difficulty concentrating, reads slowly, or simply checks finances while tired may benefit more from a short list of meaningful categories than from an elaborate structure. Cashew’s value is therefore not just in recording transactions; it is in giving users a place to create a financial view that can remain understandable.
News and Features Related to Cashew—Expense Budget Tracker

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I also recommend entering a note when a purchase might otherwise be confusing. “Market” could mean groceries, household supplies, or a shared purchase. A short description can prevent the review stage from becoming a memory test. This is a small workflow decision, but it makes the history more useful for people who need context rather than just totals.
The average rating is 4.7 from around 27 thousand ratings, and the app has passed half a million installs. That level of adoption suggests that the focused expense-tracking concept resonates with many people, but popularity should not be mistaken for universal suitability. A clean personal ledger can be excellent for one user and frustrating for another if manual entry does not fit their routine.
Don't want to read the full review?
Making the first week easier to understand
The first week is more important than the first hour. I would not try to reconstruct years of spending before deciding whether Cashew is useful. Instead, I would record purchases as they happen and review the result after several days. This gives the app a realistic sample of your behavior and gives you a chance to see whether the categories make sense.
A useful technique is to make the entry moment part of an existing action. For example, after paying for lunch, I would record it before putting the phone away. After an online order, I would add it once the confirmation screen is closed. Connecting the expense to an event is easier than promising to remember everything at night, when several transactions may already be blurred together.
Screenshots
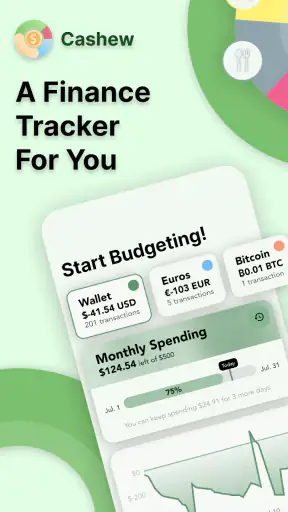
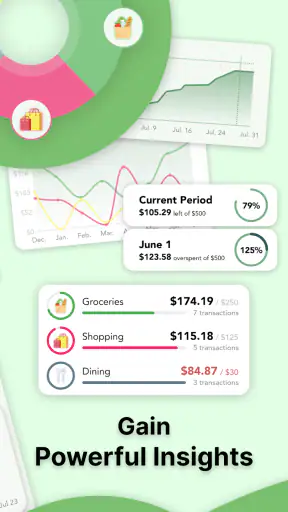
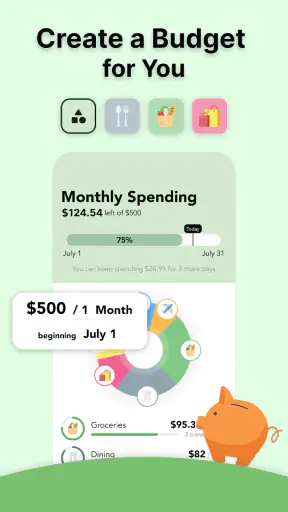
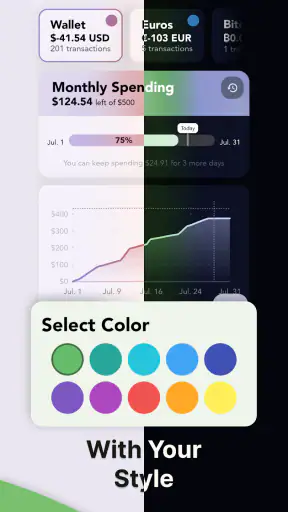
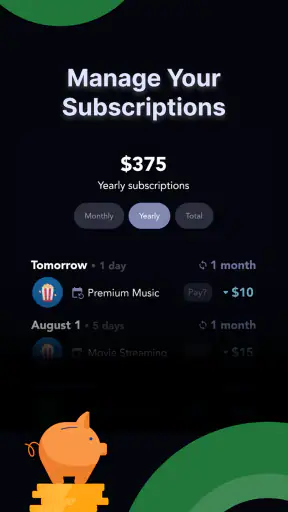
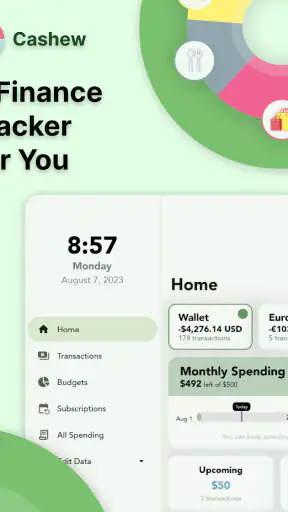
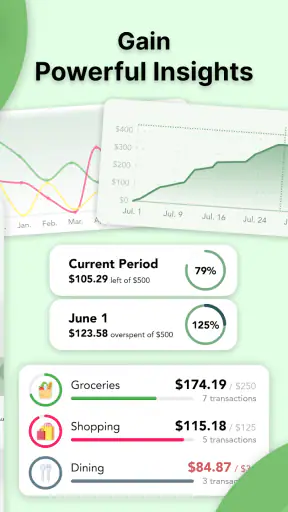
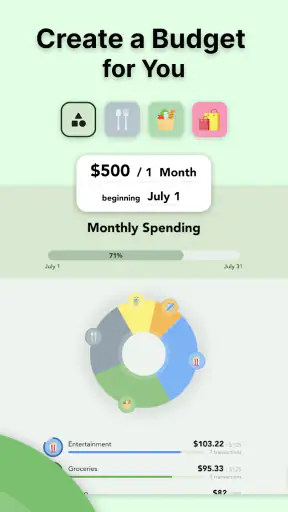
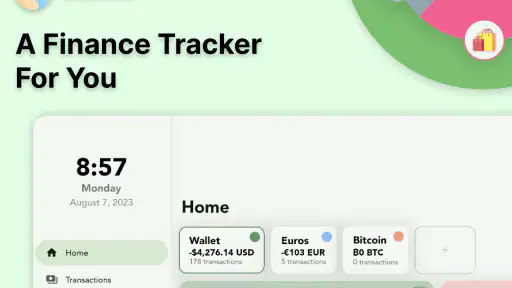
For users with limited attention or memory challenges, this approach reduces the number of decisions made at once. The goal is not perfect accounting; it is consistent enough information to guide choices. If a missed entry makes someone abandon the entire system, the app becomes less useful than a simpler note-taking method. Cashew is most helpful when the user treats it as a practical feedback loop rather than a test of financial discipline.
Another worthwhile habit is a short weekly review. I would look for one category that grew unexpectedly, one recurring cost that deserves attention, and one budget limit that was unrealistic. This is more actionable than staring at a total without asking what should change. It also helps users who find long financial sessions overwhelming because the review can remain focused and predictable.
Using Cashew across different abilities and situations
Motor and sensory considerations
Expense tracking can create motor demands that are easy to overlook. Repeated typing, selecting categories, correcting amounts, and navigating back to a budget may become tiring for someone with limited dexterity, tremors, joint pain, or one-handed phone use. Cashew’s manual nature means the user should test whether entering a typical purchase feels comfortable before committing to it as a daily system.
I would keep entries short and avoid trying to write a full explanation for every transaction. A category, amount, and brief label are often enough for a useful record. This reduces repeated typing and makes corrections less burdensome. If a user shares finances with another person, agreeing on a small set of category names can also prevent unnecessary editing and reclassification.
People with low vision or visual fatigue should pay attention to whether the text, controls, and visual summaries remain comfortable on their particular device. I would not assume that a finance app automatically meets every person’s needs simply because its interface looks uncluttered. Screen size, display settings, font preferences, contrast, and familiarity with Android navigation can all change the experience.
For users who are sensitive to visual density, a focused tracker may be easier to approach than a banking application that combines many financial services on one screen. On the other hand, anyone who relies heavily on spoken interaction or needs highly specialized input support should try the core tasks directly before depending on the app. Recording an expense is the real test, not merely opening the dashboard.
Color can also affect interpretation. Budget summaries often use visual cues to distinguish normal spending from a limit that is close or exceeded. I would encourage users not to rely on color alone when making decisions. Read the amount and category, and use the numerical information as the final check. This is a good habit for anyone, especially people with color-vision differences or screens that are difficult to view in bright sunlight.
Situational access in real life
Cashew makes the most sense in situations where a person wants control without connecting the process to a bank account. A student could use it to separate food, transport, and discretionary purchases. A household could use it to observe shared spending patterns, provided everyone agrees on who records which transactions. Someone preparing for a move could create a temporary spending routine and watch how quickly small purchases accumulate.
Consider a realistic weekday. I buy coffee in the morning, pay for a bus ride, pick up groceries after work, and make a small online purchase at night. If I enter each item close to the moment it happens, the app can turn those scattered decisions into a reviewable pattern. By the end of the week, I may discover that the issue is not one large purchase but several convenient purchases that were never part of the original plan.
That scenario also shows the central trade-off. Manual tracking gives me control over what gets recorded and how it is categorized, but it asks me to remember the step. A bank-linked tool may reduce that effort through automatic transaction collection, while sometimes requiring more cleanup, account permissions, or category corrections. Cashew is preferable when deliberate awareness matters more than automatic convenience.
It can also suit people who want to track cash spending. Cash is easy to lose from memory because there may be no digital statement to revisit. Entering it immediately creates a record that would otherwise disappear. The same applies to small purchases made by different payment methods: a single personal log can bring them together without requiring the user to check several accounts.
For shared budgets, I would be cautious about assuming that one person’s entries represent the whole household. The app can be useful as a shared planning reference, but the system needs an agreed routine. If one partner records groceries while the other forgets subscriptions and cash purchases, the resulting budget may look precise while still being incomplete. The limitation is not necessarily the interface; it is the reliability of the shared process.
Who should use it, and who should choose something else
I would recommend Cashew to someone who wants a dedicated place for expenses and budgets, prefers to control entries themselves, and is willing to spend a few minutes maintaining the record. It is also a sensible starting point for people who feel overwhelmed by complex personal-finance software. The app’s Everyone age rating makes it broadly approachable, though younger users may still need guidance when interpreting budgets and distinguishing needs from wants.
I would be more hesitant to recommend it to someone who expects automatic synchronization across financial accounts, advanced investment tracking, tax preparation, or a complete household accounting system. Those users may be better served by a banking platform or a more comprehensive finance package. The focused design is an advantage only when the user’s goal is focused.
It may also be a poor fit for someone who repeatedly forgets manual entries and does not want to build a reminder habit. No expense tracker can produce a trustworthy picture from missing transactions. In that situation, an automatic alternative may be more practical, even if it requires occasional corrections. Choosing the app with the least impressive feature list is sometimes the right decision if it is the one you will actually keep using.
Practical barriers that remain
The largest barrier is consistency. A person can understand the screens perfectly and still gain little value if purchases are entered several days late. Delayed entry also increases the chance of forgetting cash payments, splitting a purchase incorrectly, or assigning it to a vague category. I would treat the app as a habit tool and establish one reliable entry point in the day rather than depending on motivation.
There is also a privacy and control trade-off to consider. Manual tracking avoids the need to make the app a central connection to every financial account, but it places responsibility on the user. Some people will appreciate that separation; others will see it as extra work. Neither preference is wrong. It depends on whether the priority is direct control or reduced effort.
Optional purchases may also influence how comfortable a user feels with the long-term experience. The app itself is free, while individual in-app purchases are listed between $1.49 and $19.99. I would explore the free experience first and decide whether any paid item solves a problem I genuinely have. A budgeting tool should reduce financial stress, not encourage spending simply because a feature looks attractive.
Device context can create another barrier. The minimum requirement of Android 7.0 makes the app available to many older phones, but a compatible operating system does not guarantee that every person will find the display comfortable. Small screens, aging batteries, slow performance, or difficult touch input can affect a finance routine. I would test the complete process on the phone that will be used every day, not just on a newer device in a store.
My inclusive verdict
After using Cashew as a focused expense and budget tool, I see it as a good option for people who want financial information presented in a manageable way and who are comfortable taking responsibility for their own entries. Its strongest inclusive quality is the possibility of keeping the system simple: fewer categories, shorter notes, and brief reviews can make the routine less demanding for users with limited time, attention, or energy.
Its limitations are equally important. Manual input can be tiring for some users, difficult for people who forget transactions, and unsuitable for anyone expecting automatic account-based tracking. The app does not become accessible merely because it is focused; each person still needs to check how reading, tapping, typing, and reviewing feel on their own device and with their own abilities.
The current version, 6.6.11, gives Android users on version 7.0 or newer a straightforward way to try the workflow without an upfront price. I would start with a small set of categories, record purchases at the moment they happen, and review the pattern weekly. If that routine feels natural, Cashew can become a useful personal money dashboard. If the entry process feels like another chore or automatic collection is essential, a different finance app will probably serve you better.
My recommendation is therefore positive but specific: choose Cashew when you want a clear, self-managed spending habit rather than a fully automated financial suite. It is most valuable when its simplicity matches your needs, and most frustrating when you expect it to remove the work of tracking altogether.
Cashew—Expense Budget Tracker FAQ
What is Cashew—Expense Budget Tracker used for?
Cashew—Expense Budget Tracker is a personal finance app designed to help you record expenses, organize transactions, monitor income, and understand where your money goes. It can be useful for creating budgets, tracking spending habits, and reviewing financial activity from one place. The app is best suited to users who want a clearer overview of everyday finances without relying on spreadsheets.
Can I create budgets and track spending categories in Cashew?
Yes, Cashew is built around budgeting and expense organization. You can generally assign transactions to categories, set spending limits, and compare your actual expenses with your planned budget. This makes it easier to identify categories where you regularly overspend. Before downloading, check the current version’s available category, budget-period, and customization options, as features may differ between platforms or app updates.
Does Cashew support recurring transactions and scheduled payments?
Cashew includes tools intended to make regular financial entries easier to manage, which can be helpful for rent, subscriptions, salary, bills, and other repeating transactions. Recurring entries reduce the need to add the same information manually every month. However, users should confirm whether the specific recurring-payment rules they need are supported, especially for variable amounts, reminders, or automatic date adjustments.
Is my financial information safe when using Cashew?
Because a budgeting app may contain sensitive information about spending, accounts, and income, privacy and security should be considered before use. Cashew’s protection depends on the app’s current storage, synchronization, backup, and device-lock features. Avoid entering unnecessary confidential details, use a secure device passcode, and review the developer’s privacy policy and permissions before enabling cloud services or sharing data across devices.
Is Cashew free, and are there any limitations or in-app purchases?
Cashew may offer a free way to begin tracking finances, while some advanced tools can depend on the app’s current pricing model, platform, or premium plan. Potential restrictions may involve synchronization, reports, customization, backups, or additional budgeting features. Since prices and included features can change, review the Google Play Store or Apple App Store listing carefully before downloading and check whether subscriptions renew automatically.











